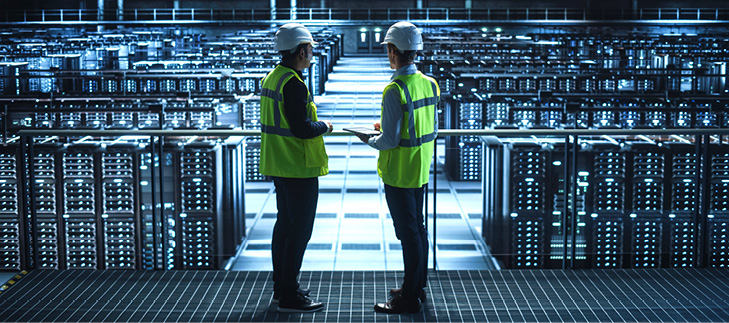
North America is in the midst of a new kind of infrastructure boom. It is no longer simply highways, bridges and airports. Today’s critical assets are data centers, fiber networks, 5G and next-generation wireless technologies, cloud facilities, edge-computing sites and more, along with the power and cooling systems that support them.
The stakes and opportunities are significant. The construction industry has the expertise to build this digital future and a responsibility to do so safely and with the right risk and insurance strategies. These projects, however, present unique challenges for contractors, who must navigate rapidly changing technologies, complex networks of stakeholders, and stringent performance and cybersecurity requirements, all while managing traditional construction risks.
Because these projects are large, complex and risk-intensive, delivering them reliably and on budget requires a coordinated, multiline insurance strategy that addresses construction, digital and energy-related risks every step of the way. These exposures are closely connected: a design error can affect power availability, a delayed component can disrupt commissioning, and a construction incident can jeopardize contractual service dates. In this infrastructure boom, insurance is not just a source of capacity. Insurers that understand data center technology, project phasing and evolving risk profiles can help structure coverage, risk engineering and claims support in ways that keep projects on track and, once built, support their long-term protection.
Why digital infrastructure matters
Digital infrastructure forms the digital backbone of everyday life, supporting AI and new technologies that shape how we all live, work, learn and do business. It is becoming as essential to economic activity as more traditional forms of infrastructure. It must be reliable because uptime is critical. When a data center goes down, business operations and access to essential services can be disrupted. It must also be resilient in the face of physical, environmental and digital threats. When a major fiber route is delayed or damaged, communities can lose essential services and economic opportunities.
Scalability is also critical. Technology changes quickly, so the infrastructure supporting it will need to change too. Digital infrastructure must also be defensible because regulators, investors and communities are watching closely, including how projects manage reliability, energy use, environmental impacts and local concerns.
Setting the project up for long-term success goes beyond meeting technical specifications. It means anticipating where things can go wrong and how projects can fail, understanding the financial and operational impact, and designing effective risk-mitigation and risk-transfer strategies that support recovery and continuity. It also means making sure that, when the unexpected happens, the impact on the organizations involved and local communities is limited.
Managing these exposures as a connected system can help contractors protect schedules, capital and long-term performance.
Managing the risks of high-value digital infrastructure projects
The rapid growth of digital infrastructure requires insurance capacity measured in billions. Data centers concentrate substantial value and operational risk in one location. An appropriately structured insurance program can provide developers and investors with greater confidence to move these complex, capital-intensive projects forward.
Especially during construction, risks can cause significant financial losses or stop a project altogether. Builder’s Risk is central because data center and other digital builds concentrate substantial value at a single site. Data center construction is exposed to fire, water damage, electrical faults, accidental damage, theft, vandalism and breakage of high-value mechanical, electrical and IT equipment. Any one of these events can wipe out months of progress, derail the schedule and trigger additional costs or contractual liabilities tied to power-up dates or service-level commitments.
Beyond property risk, supply-chain exposure is significant. These projects depend on a wide range of specialist subcontractors: high-voltage electricians, precision cooling teams, controls and automation experts, and others. The concern is not just poor workmanship, but the risk of a key participant withdrawing from the project or failing to deliver. When that happens, chain reactions follow. For projects where revenue starts the day the facility goes live, a default can translate directly into lost income and strained relationships with customers and utilities. Subcontractor Default Insurance (SDI) can help contractors manage the financial consequences of a subcontractor default, alongside rigorous prequalification, monitoring and contingency planning intended to limit disruption to the project schedule.
Serious casualty exposure is widespread on large project sites. High-voltage systems, heavy lifting, confined spaces, fuel storage and dense activity all increase the likelihood of worker injuries, damage to neighboring property and claims of unsafe conditions. Primary Casualty policies provide the first layer of protection, but given how severe accidents can be on these megaprojects, high Excess Casualty limits may also be required. A single major event, such as a worker injury, fuel explosion or crane collapse, can trigger multiparty litigation, not to mention a multimillion-dollar settlement. Without sufficient casualty limits, the financial consequences for a contractor could be substantial.
Digital infrastructure projects rely on advanced engineering, including electrical and structural design, power systems, thermal management, grid interconnection and energy modeling. An engineering error could mean that the site cannot deliver the promised capacity or suffers instability. It may also require costly remedial work. Professional Liability coverage can respond to covered claims arising from design errors or omissions that lead to missed obligations, reduced revenue and expensive remedial work.
Data centers and energy facilities pose environmental risks during construction and operations. Fuel, cooling water, stormwater controls and emissions, including noise, vibration and air pollutants, can result in incidents that require cleanup. Environmental insurance may respond to cover sudden or gradual pollution events, including cleanup and remediation costs, regulatory actions and third-party claims, depending on the policy terms and the circumstances of the event.
These coverages address distinct exposures, but their value depends on how well they work together across the project’s design, construction and operating model.
Energy risk runs through all of this. According to JLL’s North America Data Center Report, Midyear 2026, more than 66 gigawatts (GW) of data center capacity is under construction in North America. This represents an electricity requirement greater than Germany’s. Modern data centers sit within complex energy networks. When substations, onsite generation, large-scale battery storage and advanced grid controls are added, they introduce additional risks, including cascading electrical faults, battery fires, grid instability and fuel-handling accidents.
A multiline insurance program needs to view the entire energy chain as one connected risk landscape. Coordinating builder’s risk for energy assets, casualty coverage for high-hazard work, environmental protection for fuels and batteries, and professional liability for power-system design all come back to one question: What happens financially and operationally if the energy system does not perform as planned?
Managing risk every step of the way
While risk engineering often works in the background, it can be just as important as insurance coverage in protecting a project. Construction risk engineers support a project from planning to completion by anticipating issues, improving safety and quality, helping to protect schedules and budgets, and reducing the potential impact of a loss on the overall investment.
From an SDI exposure perspective, specialist teams assess the financial strength, capacity and track record of contractors and key suppliers to identify the potential for defaults, delays and poor-quality work. Risk engineers also develop and review safety plans and site procedures to help manage and document risks systematically across the project.
They look for design weaknesses, evaluate fire protection and electrical systems, and review the placement of batteries, generators and fuel to help reduce the likelihood and impact of major incidents. For digital infrastructure specifically, they focus on controls intended to prevent arc flashes, battery fires, fuel spills, cooling failures and cascading outages during extreme weather. They also advise on site safety and emergency response planning. Because some megaprojects have thousands of workers on site at the same time, they can help project teams identify and manage potential clashes between concurrent activities.
The value of construction risk engineering can show up in fewer insurance claims and lower financial losses. It can also contribute to safer, more resilient sites. By engaging early and staying involved throughout the project, risk engineers can help project teams identify emerging exposures, assess their potential consequences and determine how they can be better managed.
In a world that grows more digital every day, connectivity and resilience are mission critical. Contractors who treat risk as a core part of how projects are designed and built set themselves up for greater success in this infrastructure boom. They will not just help build the next generation of infrastructure. By managing interconnected construction, energy and technology risks from planning through operation, they can help determine which projects stand the test of time.